
By Alfonso Davis October 4, 2026
If your card batch is larger than the amount deposited into your bank, the processor may be deducting processing fees before funding you. In a daily discount vs monthly discount merchant account, daily billing may collect fees from each settlement, while monthly billing generally lets fees accumulate and collects them separately later.
For example, your POS may show an $8,450 settled batch while only $8,274.62 appears in the bank. The $175.38 difference does not automatically mean transactions are missing. It may be processing fees or another settlement adjustment.
The fastest way to find the answer is to follow the money in this order:
POS or gateway batch → processor settlement report → bank deposit → merchant statement
There is one important distinction to understand before you begin. Daily versus monthly billing describes when processing fees are collected. Gross versus net settlement describes how those charges affect funding. A processor can even use daily billing while still depositing the gross batch and taking the daily fee as a separate debit.
That distinction prevents one of the most common reconciliation mistakes: assuming every smaller deposit is daily discount or every full deposit is monthly billing.
Daily Discount vs Monthly Discount Merchant Account Billing at a Glance
Here is the practical difference.
| Issue | Daily Discount / Daily Billing | Monthly Discount / Monthly Billing |
| When processing fees leave | Daily or around each settlement | Periodically, commonly monthly |
| What reaches the bank | May be net, or gross with a separate daily fee debit | Commonly gross or closer to gross |
| Matching deposits to batches | Often harder with net settlement | Often easier with gross settlement |
| Cash kept during the month | Less when fees leave daily | More until the later fee debit |
| Large periodic fee debit | Usually smaller or absent for fees already collected | Can be substantial |
| Fee visibility | Can be spread across many settlements | Often easier to isolate |
| Automatically cheaper? | No | No |
| Automatically changes interchange? | No | No |
| Better choice | Depends on bookkeeping and cash controls | Depends on bookkeeping and cash controls |
Current Shift4 documentation illustrates why merchants should not treat all of these terms as interchangeable. It documents Monthly Gross Billing, Daily Net Billing, and Daily Gross Billing as three separate arrangements.
Under Daily Net Billing, processing fees reduce the day’s batch funding. Under Daily Gross Billing, the merchant receives the gross batch while fees are separately debited.
For the processor-specific example and current terminology, see Shift4 payment-processing billing options.
The daily discount vs monthly discount merchant account comparison is therefore mainly about fee timing and settlement presentation. It does not, by itself, tell you whether the underlying pricing is better.
What Daily Discount Actually Means
Daily discount generally means some or all applicable processing charges are collected as processing activity settles instead of waiting until a later billing cycle.
The simplest version is daily net settlement.
Suppose you have:
- Gross settled batch: $10,000
- Processing fees deducted: $245
- Other adjustments: $0
- Bank deposit: $9,755
The calculation is straightforward:
$10,000 – $245 = $9,755
Your bookkeeper should not conclude that card sales were only $9,755. In this simplified example, the underlying card activity was $10,000 and $245 was deducted for processing.
Daily billing does not always mean a smaller deposit
This is where merchant statements can become confusing.
A processor may instead deposit the entire $10,000 and separately debit $245 from the bank that day. That is still daily fee collection, but it is not net funding.
Shift4’s current documentation explicitly demonstrates both approaches: daily net billing and daily gross billing.
That is why you need to identify the processor fee billing method and the funding method separately.
What Monthly Discount Billing Means
Monthly discount generally means processing charges accumulate during a billing period and are collected later instead of being fully deducted from each day’s settlement.
Using the same example:
- Settled batch: $10,000
- Bank deposit: $10,000, assuming no other settlement adjustments
- Processing fees accumulated: $245
- Later fee debit: $245
The merchant has temporarily retained the $245 in its bank account, but the expense has not disappeared.
Gross funding does not mean cheaper processing.
If the contractual processing charges remain $245, taking $245 next month rather than taking it today changes cash timing—not the underlying $245 cost.
When reviewing a daily discount vs monthly discount merchant account, always separate these two questions:
- When are my fees collected?
- How much am I actually being charged?
They are not the same question.
Why Deposits Don’t Match Batch Totals
When deposits don’t match batch totals, daily processing fees are one possible cause, not the only one.
Depending on the processor and settlement arrangement, differences can also come from:
- refunds;
- disputes or chargebacks;
- settlement adjustments;
- reserve activity;
- manual corrections;
- transactions grouped into a different settlement;
- a separate fee debit;
- other processor-account movements.
PayPal/Braintree’s current Disbursement & Fee Report documentation describes its report as the record merchants use to tie bank deposits back to transaction activity, track fees, and investigate refunds, disputes, adjustments, reserve holds, and manual corrections.
See PayPal/Braintree Disbursement & Fee Report documentation for the first-party reconciliation framework.
The practical rule is:
A single mismatch is a clue. A repeated, predictable difference that matches documented processing charges is much stronger evidence of net daily billing.
How to Confirm Your Billing Method From One Deposit and One Batch
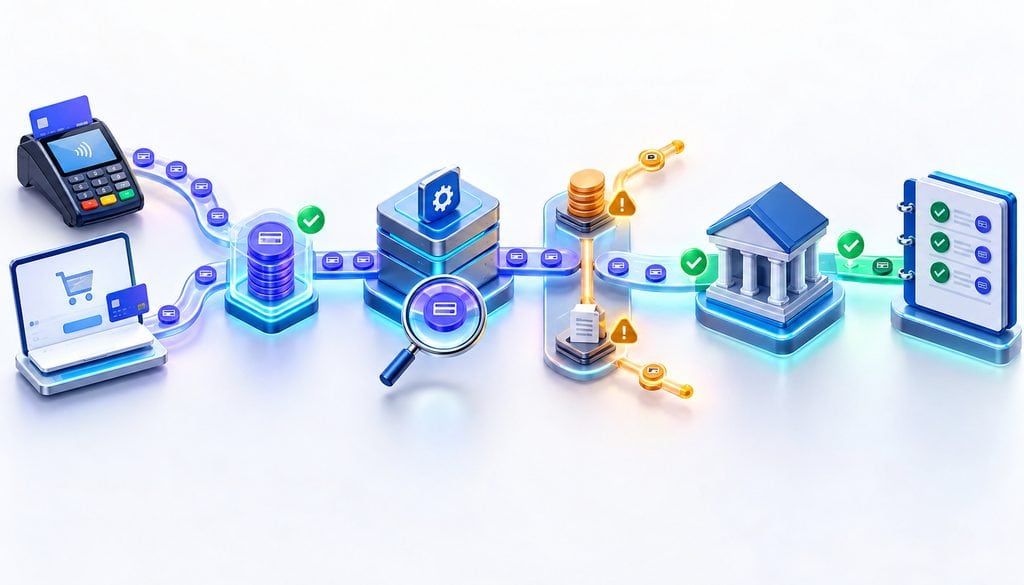
You do not need to reconcile three months of statements to get started.
To identify a daily discount vs monthly discount merchant account, begin with one clean settlement.
Step 1 — Choose a simple settlement day
Pick a day without a known large refund, chargeback, unusual adjustment, or other exceptional activity.
The cleaner the settlement, the easier it is to understand the funding method.
Step 2 — Record the settled batch
Pull the POS or gateway batch report.
Use the final settled or closed batch rather than simply adding authorizations that may not all have settled.
Example:
Gross batch: $8,450.00
Step 3 — Find the processor’s corresponding settlement
Locate the payout, settlement, funding, or transfer record connected with that batch.
Depending on the processor, the batch date and bank posting date may not be identical. Use a settlement ID, transfer ID, batch ID, or comparable reference when available.
Step 4 — Match the bank deposit
Suppose the bank received:
$8,274.62
Calculate the difference:
$8,450.00 – $8,274.62 = $175.38
You now have one job: explain the $175.38.
Step 5 — Look for the deduction
Check the processor’s settlement detail for charges or adjustments totaling $175.38.
Depending on the account, the settlement report may contain processing charges, refunds, dispute activity, reserve movements, or other adjustments.
Do not rely on the label alone. Processor terminology varies.
Step 6 — Check the merchant statement
Determine whether the statement reports that $175.38 as fees already collected or shows additional charges that will be debited separately.
A fee appearing on the monthly statement does not automatically mean it was charged twice. Statements can report charges that were already deducted from settlements.
Step 7 — Ask the processor a precise question
Instead of asking, “Why are my deposits short?” ask:
“Please confirm whether my processing fees are collected daily or periodically. Also confirm whether my funding is net settlement, gross settlement with separate daily fee debits, or gross settlement with fees collected later. Please identify which charges follow each billing method.”
Ask for the answer in writing.
That gives you something concrete to compare with your settlement report and next merchant statement.
Gross vs Net Settlement Deposits
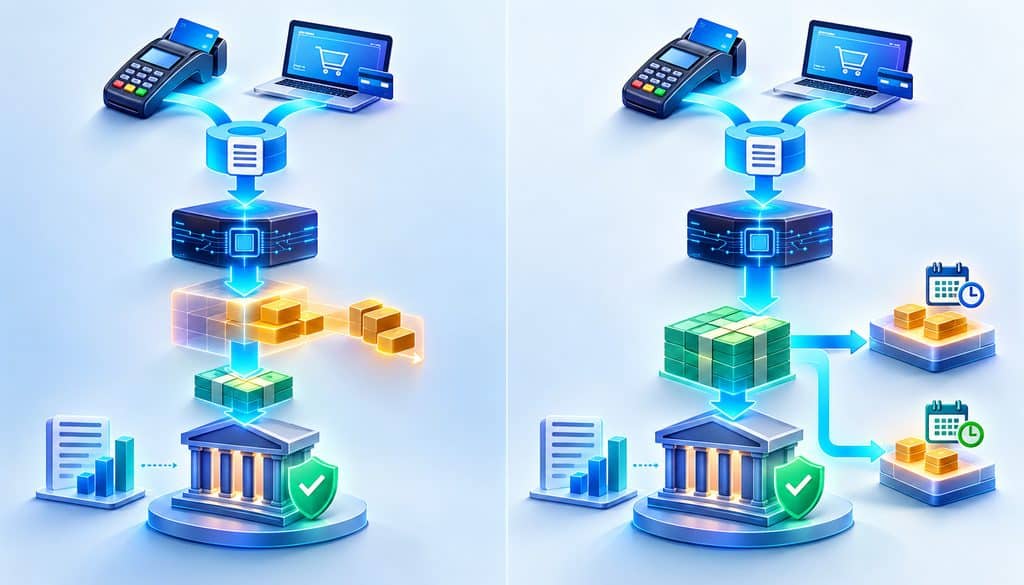
Understanding gross vs net settlement deposits makes reconciliation much easier.
Net settlement
The flow normally looks like:
Customer payments → settled batch → deductions → bank deposit
Example:
$10,000 settlement – $245 processing fees = $9,755 deposit
Gross settlement
The basic flow looks like:
Customer payments → settled batch → bank deposit → processing fees collected separately
Example:
$10,000 settlement → $10,000 deposit → $245 later fee debit
But there is another possibility:
$10,000 settlement → $10,000 deposit → $245 same-day separate debit
That is why gross vs net settlement deposits should not be used as perfect substitutes for “monthly” and “daily.”
Daily billing can be gross or net depending on processor configuration.
The Accounting Problem Net Deposits Can Create
The daily discount vs monthly discount merchant account decision can change your bookkeeping workflow even when it does not change total processing expense.
The biggest risk is recording the bank deposit as though it were the actual amount of sales.
Consider:
- Customer card sales: $10,000
- Processor fees: $245
- Bank deposit: $9,755
Conceptually, you want the accounting records to preserve:
- Gross card revenue/activity: $10,000
- Processing expense: $245
- Cash received: $9,755
This is an accounting illustration, not individualized accounting or tax advice. Your accountant should determine the proper entries for your accounting method and chart of accounts.
If only $9,755 is recorded as sales, the business may lose visibility into:
- actual gross sales;
- processing-fee expense;
- gross-margin analysis;
- location or channel performance;
- processing-cost calculations;
- period-to-period financial comparisons.
The problem is not daily discount itself. The problem is posting a net cash movement without accounting for the components that created it.
A Simple Clearing-Account Method
A merchant clearing account can make the reconciliation easier.
The workflow is:
Gross Sales → Merchant Clearing Account → Processing Expense → Bank Deposit
Using the $10,000 example:
- Record the $10,000 of card activity.
- Move the amount expected from the processor into a clearing account.
- Record the $245 processing deduction.
- Record the $9,755 bank deposit.
- Confirm that the settlement has cleared as expected.
Under monthly billing, the process changes slightly because the gross deposit and fee debit occur at different times.
A clearing account can handle either arrangement as long as the bookkeeping workflow matches the actual processor reports.
Give your bookkeeper these five records
Provide:
- POS or gateway batch report.
- Processor settlement report.
- Bank activity.
- Merchant processing statement.
- Current pricing schedule or merchant agreement.
Those documents let the bookkeeper separate sales, processing expense, and cash rather than trying to reconstruct everything from the bank feed.
How to Calculate Your Real Monthly Processing Cost
A useful merchant statement reconciliation discount method should look beyond individual deposits.
Once the month closes, calculate:
Effective processing cost = total verified processing-related charges ÷ gross processed card volume
Example:
- Monthly card volume: $120,000
- Verified processing-related charges: $3,360
Calculation:
$3,360 ÷ $120,000 = 0.028 = 2.80%
The 2.80% result is useful as a monitoring number.
It does not automatically tell you that your pricing is good or bad. Transaction type, card mix, processor markup, network costs, ticket size, fixed charges, and other contractual terms can affect the result.
What matters is the trend.
If your effective cost was 2.60% and then becomes 2.80%, investigate what changed.
Do not assume the processor increased its markup until you can identify the line items responsible.
Why Daily Deductions Can Make Fee Changes Harder to Spot
Daily billing can be completely accurate and properly disclosed.
The challenge is visibility.
One $3,000 monthly processor withdrawal is easy to notice. Dozens of smaller settlement deductions can be harder to monitor unless the accounting system tracks them separately.
Review the account more closely when:
- settlement deductions cannot be tied to processor reporting;
- a new fee appears on the statement;
- your effective processing cost rises without a clear reason;
- processor support cannot explain which charges are taken daily;
- a fee seems to reduce settlement and then cause another bank debit;
- recurring adjustments remain unexplained;
- the pricing schedule and statement no longer appear to match.
These are reasons to investigate, not proof of overbilling.
When an unexplained charge appears to come from the contract rather than the settlement process, compare it with the fee language and conditions in your agreement. The practical checks for identifying hidden fees in merchant service agreements fit naturally at that stage.
Daily vs Monthly Discount — 30-Day Cash-Flow Example
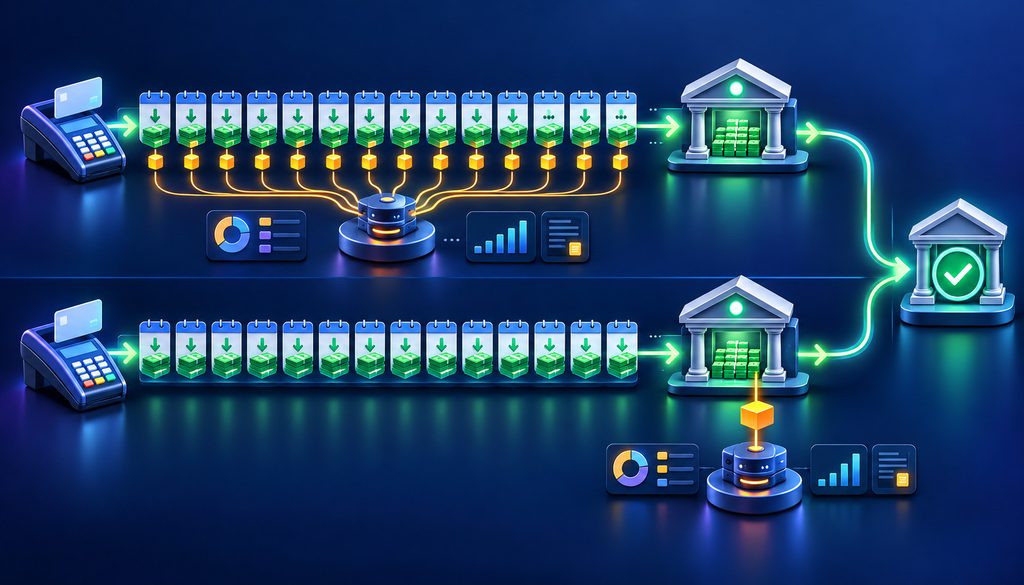
The easiest way to understand a daily discount vs monthly discount merchant account is to hold every other variable constant.
Assume:
- Monthly settled card sales: $100,000
- Total processing charges: $2,700
- No refunds, disputes, reserves, or other adjustments
Daily net settlement
If all $2,700 is collected from settlements during the month:
$100,000 – $2,700 = $97,300
Approximately $97,300 reaches the bank.
Monthly gross settlement
If the merchant receives the full $100,000 during the month and the processor later debits $2,700:
$100,000 – $2,700 = $97,300
The simplified ending amount is still:
$97,300
The important differences are:
- timing;
- deposit visibility;
- bank reconciliation;
- accounting workflow;
- cash management.
Monthly billing has not created an extra $2,700. It has simply delayed when that $2,700 leaves the account.
Cash-Flow Tradeoffs
Advantages of daily collection
Daily collection may help a merchant:
- pay processing costs gradually;
- avoid one large periodic fee debit for amounts already collected;
- reduce the risk of spending money needed for the processing bill.
Disadvantages of daily collection
It may also create:
- smaller daily deposits under net settlement;
- more reconciliation work;
- lower fee visibility;
- a greater need for clearing-account reporting.
Advantages of monthly collection
Monthly billing may provide:
- deposits that more closely resemble settlement totals;
- easier batch-to-bank matching;
- more visible processing expense;
- easier month-end variance review.
Disadvantages of monthly collection
The merchant must be prepared for:
- a larger periodic debit;
- the need to reserve cash for that debit;
- possible overdraft or cash-flow pressure if the expected withdrawal is not planned for.
Temporarily keeping processing-fee cash is not “free working capital.” It remains money that will be needed to satisfy processing charges if the underlying pricing remains unchanged.
Which Billing Method Makes Reconciliation Easier?
For many accounting teams, a daily discount vs monthly discount merchant account is easier to reconcile under gross funding because the bank deposit more closely resembles the corresponding settlement.
That does not mean monthly billing is universally better.
| Priority | Method That May Be Easier |
| Match daily deposits closely to settlements | Gross funding |
| Avoid a large periodic processor debit | Daily collection |
| See processing fees separately | Often gross funding |
| Automate detailed settlement reconciliation | Either |
| Maintain tighter cash discipline | Daily collection may help |
| Perform controller-led variance analysis | Often monthly billing |
| Minimize manual deposit adjustments | Often gross funding |
Modern processor reporting can make net settlement highly manageable when the system is configured correctly.
The most important control is not which method you choose. It is whether every settlement can be traced from transaction activity to processor reporting and finally to the bank.
PayPal/Braintree describes this exact reconciliation purpose for its disbursement reporting: tying bank deposits back to transaction activity and showing the components responsible for the transfer.
How to Switch to Monthly Discount Billing
If you want to switch to monthly discount billing, ask the processor several questions before authorizing the change.
1. Confirm the current configuration
Ask whether your account currently uses:
- daily fee collection;
- monthly fee collection;
- net funding;
- gross funding with separate daily debits;
- gross funding with later fee collection;
- or another hybrid configuration.
Do not assume “daily discount” tells you everything.
2. Ask whether monthly billing is available
Processor platforms and account arrangements vary.
A feature offered by one processor should not be presented as an industry-wide requirement.
3. Ask exactly what changes
Request written clarification covering:
- fee-collection timing;
- funding presentation;
- monthly bank-debit process;
- fees included in the change;
- fees excluded from the change;
- effective date;
- reserve treatment;
- settlement timing;
- any account amendment required.
4. Ask whether the pricing changes
This is critical.
Ask:
“Does changing my processing-fee billing method alter my processor markup, per-transaction charges, monthly charges, contract term, reserve requirement, settlement timing, or any other pricing provision?”
Then ask:
“Is this only a change in when fees are collected, or does my pricing schedule change too?”
5. Get the answer in writing
Keep the processor’s written confirmation with your agreement and pricing records.
It should state the new billing method and effective date.
6. Verify the first complete billing cycle
After you switch to monthly discount billing, compare:
- batch totals;
- processor settlement totals;
- bank deposits;
- separate processor debits;
- statement fees;
- current pricing schedule.
A larger daily deposit proves only that funding changed. It does not prove that pricing stayed the same.
Does a Billing-Method Change Affect Interchange?
A processor fee billing method should not be confused with interchange.
Visa’s current U.S. interchange documentation describes interchange reimbursement fees as transfer fees between financial institutions. It separately explains that merchants pay a merchant discount to their financial institution for card-acceptance and processing services.
You can review the distinction in the Visa U.S. interchange reimbursement fee documentation.
That means changing when your processor collects its charges should not automatically be described as changing Visa interchange.
However, that does not guarantee your processor will make the billing change with no pricing consequences.
One processor may change billing frequency without repricing. Another may attach different commercial terms to the requested configuration.
For a daily discount vs monthly discount merchant account, always obtain the proposed pricing conditions before agreeing to the change.
Monthly Billing Does Not Automatically Mean Transparent Pricing
A merchant can receive full daily deposits and still have confusing pricing.
A merchant can also receive net deposits and have completely accurate, clearly disclosed pricing.
Settlement method and pricing transparency are different issues.
Review:
- gross processing volume;
- processing-fee total;
- processor markup;
- transaction fees;
- recurring account charges;
- applicable network-related costs;
- adjustments;
- credits;
- refunds;
- disputes;
- other contractual charges.
When you need to evaluate how clearly the fee structure itself is presented, the discussion of transparent merchant-services pricing provides a natural next step without confusing pricing structure with settlement timing.
Real-World Reconciliation Example
Suppose four daily settlements look like this:
| Batch Date | Gross Batch | Processing Fee | Other Deduction | Bank Deposit | Reconciled? |
| Oct. 1 | $8,420.00 | $202.08 | $0.00 | $8,217.92 | Yes |
| Oct. 2 | $9,135.00 | $219.24 | $125.00 | $8,790.76 | Yes |
| Oct. 3 | $7,890.00 | $189.36 | $0.00 | $7,700.64 | Yes |
| Oct. 4 | $10,355.00 | $248.52 | $75.00 | $10,031.48 | Yes |
| Total | $35,800.00 | $859.20 | $200.00 | $34,740.80 | Yes |
Check the math:
$35,800.00 – $859.20 – $200.00 = $34,740.80
The accountant can therefore identify:
- Gross card activity: $35,800.00
- Processing expense: $859.20
- Other identified deductions: $200.00
- Bank funding: $34,740.80
Nothing is unexplained.
Now imagine the bank actually received $34,500.80.
The unexplained difference becomes:
$34,740.80 – $34,500.80 = $240.00
That $240 should remain an open reconciliation item until it can be tied to a specific processor entry.
This is the correct way to investigate situations where deposits don’t match batch totals: reconcile the difference instead of guessing what caused it.
How to Tell Whether a Processing Fee Was Charged Twice
Suppose the settlement report shows:
- Gross batch: $10,000
- Processing fee deducted: $245
- Deposit: $9,755
Then the merchant statement also lists $245 of processing charges.
That does not prove another $245 was taken.
The statement may simply be reporting fees already deducted.
Check the bank activity.
If no second $245 withdrawal occurred, you may be seeing a statement summary rather than duplicate billing.
If another $245 was withdrawn, determine whether it represents:
- the same processing charges;
- monthly account fees;
- another billing period;
- a separate fee category;
- or an actual duplicate deduction.
A practical merchant statement reconciliation discount method should therefore trace every suspected duplicate through three places:
settlement report → statement → bank activity
Only after confirming that the same obligation actually reduced cash twice should it be treated as a potential duplicate charge.
A 10-Minute Merchant Statement Audit
Once each month, check:
- Gross processed card volume.
- Transaction count.
- Total processing charges.
- Fees deducted from settlements.
- Separate processor bank debits.
- Fixed recurring charges.
- Refunds.
- Disputes and chargebacks.
- Adjustments.
- Reserve activity if applicable.
- Effective processing cost.
- Any fee that appears to have reduced cash twice.
- Whether current charges match the pricing schedule.
- Whether unexplained items remain in the clearing account.
If a number cannot be traced, investigate it.
Do not label it an overcharge until you know what produced it.
Daily Discount vs Monthly Discount Merchant Account Checklist
Before making a change:
- Pull one clean settled batch.
- Find the corresponding processor settlement.
- Match the settlement to the bank.
- Explain every difference.
- Identify whether processing fees are collected daily or periodically.
- Determine whether funding is gross or net.
- Look for separate daily processor debits.
- Look for monthly processor debits.
- Calculate your effective monthly processing cost.
- Compare statement charges with your pricing schedule.
- Ask whether monthly billing is available.
- Ask whether changing billing methods changes pricing.
- Get the requested change in writing.
- Verify the first complete billing cycle after the change.
- Update the bookkeeping procedure.
Frequently Asked Questions
Why is my bank deposit smaller than my credit-card batch?
Your processor may have deducted processing fees before funding the settlement, but other settlement items can also create a difference. Start with the processor settlement report and reconcile it to the bank. If the same predictable difference repeatedly corresponds to processing charges, daily net billing becomes a much stronger explanation.
What is daily discount on a merchant account?
Daily discount generally means applicable processing charges are collected daily instead of accumulating entirely until a later billing cycle. Depending on processor configuration, the fees may be removed from settlement before funding or debited separately from the bank.
What is monthly discount billing?
Monthly discount generally means applicable processing fees accumulate during the billing period and are collected later. Daily deposits may therefore be gross or closer to gross, although refunds, adjustments, disputes, or other settlement activity can still cause differences.
Is monthly discount cheaper than daily discount?
Not by itself. If processor markup, transaction charges, network costs, and other contractual pricing remain identical, collecting the same fees later changes timing rather than total cost.
Can I ask my processor to switch from daily to monthly discount?
Yes. You can ask to switch to monthly discount billing, but availability depends on the processor and account configuration. Ask whether only fee timing changes or whether pricing, reserves, funding speed, contract terms, or other conditions change too.
Will changing my billing method change my processing rates?
Not necessarily, but do not assume the answer is no. Billing timing and pricing are separate concepts, yet processors may apply different commercial terms to different account configurations. Request the complete pricing impact in writing before authorizing a change.
How should I record net merchant deposits in accounting software?
Generally, the accounting workflow should preserve the underlying gross sales activity and separately identify processing expense and other deductions so the final cash amount agrees with the bank deposit. Exact ledger accounts and entries depend on your accounting method and chart of accounts, so have your accountant approve the procedure.
Choosing the Right Daily Discount vs Monthly Discount Merchant Account Setup
The right daily discount vs monthly discount merchant account setup is not necessarily the one that produces the biggest daily deposit.
Start with reconciliation.
Take one clean batch, find the corresponding processor settlement, and match it to the bank. Determine whether fees are collected daily or periodically and whether your funding is gross or net. Then identify refunds, adjustments, disputes, or other items that affect the payout.
Next, calculate your total processing cost for the month and compare it with your pricing schedule. If you plan to switch to monthly discount billing, confirm whether the processor is changing only the collection schedule or changing the pricing arrangement too.
If pricing is otherwise identical, choose the structure that gives your business better control over reconciliation and cash management.
For a daily discount vs monthly discount merchant account, the safest sequence is simple:
Reconcile the deposit first → verify the fees second → compare the pricing third → change the billing method only after the new terms are clear in writing.